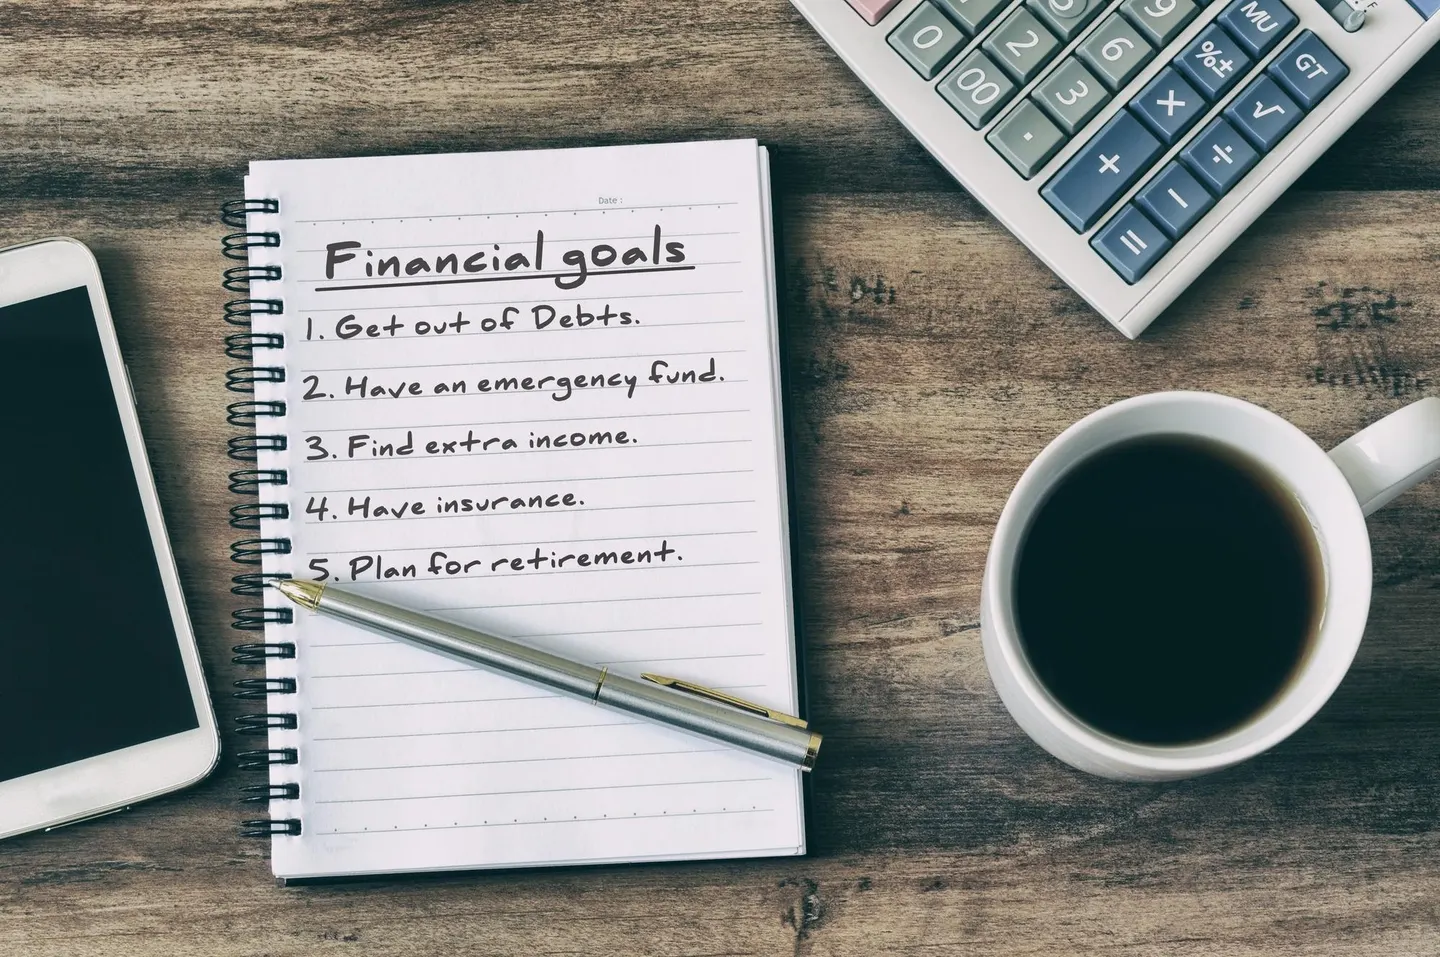
Setting financial goals gives your money a clear direction and purpose. Without defined objectives, it becomes easy to spend without intention or lose track of what you are working toward. Realistic financial goals serve as a roadmap that helps you make deliberate decisions about your income, expenses, and savings. When your goals are grounded in your actual financial situation rather than wishful thinking, you are far more likely to achieve them. This article explores how to establish financial goals that are both meaningful and attainable.
Understanding Your Current Financial Position
Before you can set realistic goals, you need a complete picture of where you stand financially right now. This means calculating your total income from all sources, including your primary job, side income, and any other regular money coming in. You should also list all your debts, such as credit card balances, student loans, car payments, and mortgage obligations, along with the interest rates attached to each one. Next, examine your monthly expenses by reviewing bank statements and credit card bills from the past three months to identify spending patterns. Understanding your net worth, which is your total assets minus your total liabilities, gives you a concrete starting point. Without this foundation, any goals you set will lack grounding in reality and become difficult to track.
Categorizing Your Goals by Time Frame
Financial goals work best when you organize them by how soon you want to achieve them. Short-term goals typically span from a few months to two years and might include building an emergency fund, paying off a specific debt, or saving for a vacation. Medium-term goals usually range from two to five years and could involve saving for a down payment on a home, funding education, or replacing a vehicle. Long-term goals extend beyond five years and often include retirement planning, building substantial wealth, or securing your children’s future education. Separating your goals by time frame helps you allocate your resources appropriately and ensures that you are not trying to accomplish everything at once. Each category requires different strategies and priorities, so treating them distinctly makes your overall plan more manageable and realistic.
Making Your Goals Specific and Measurable
Vague financial goals rarely lead to success because they lack clear benchmarks and measurable progress. Instead of saying you want to “save more money,” establish a specific target such as “save 10,000 dollars over the next two years” or “reduce monthly spending by 200 dollars.” Breaking larger goals into smaller milestones makes them feel less overwhelming and allows you to celebrate progress along the way. When you know exactly how much money you need to save and by when, you can calculate a monthly or weekly savings amount that feels more achievable. Measurable goals also help you stay accountable because you can review your progress regularly and adjust your approach if needed. According to the Consumer Financial Protection Bureau, having clear, defined financial goals is a key component of overall financial well-being.
Ensuring Your Goals Align with Your Values
Your financial goals should reflect what truly matters to you rather than what you think you should want or what others expect of you. Take time to consider your core values, whether they center on family, health, education, experiences, security, or personal growth. A goal that conflicts with your values will feel like a burden and become increasingly difficult to maintain over time. For example, if you value travel and experiences, a goal focused solely on cutting all discretionary spending will likely fail because it conflicts with what brings you fulfillment. When your goals involve complex tax considerations or long-range planning, working with a financial planner in Henderson NV can help you assess whether your targets are structured in a way that supports your overall financial picture. When your financial goals align with your genuine priorities, you develop the motivation and commitment necessary to stick with them even when challenges arise.
Accounting for Obstacles and Building in Flexibility
Realistic financial goals must account for the fact that life is unpredictable and your circumstances will likely change. As you work toward your goals, you may face unexpected expenses, job changes, health issues, or shifts in family responsibilities that require adjustments. Building a buffer into your timeline and your savings targets provides cushion for these inevitable surprises without derailing your entire plan. Regular reviews of your goals, perhaps quarterly or annually, allow you to assess what is still working and what needs modification. Flexibility does not mean abandoning your goals when they become difficult, but rather adjusting your approach when your situation genuinely changes. A realistic goal plan acknowledges that perfection is impossible and builds in room for the realities of daily life.
Conclusion
Setting realistic financial goals requires you to start with honest self-assessment, organize your objectives by time frame, and articulate them with clear measurements. Your goals should reflect your personal values and priorities rather than external pressures or unrealistic timelines. By incorporating flexibility and regularly reviewing your progress, you create a financial plan that serves your actual life circumstances rather than an idealized version of them. The process of setting and pursuing financial goals is as much about building awareness and intentionality around money as it is about reaching specific dollar amounts. Taking these steps creates a foundation for financial success that is grounded in reality and tailored to your individual situation.